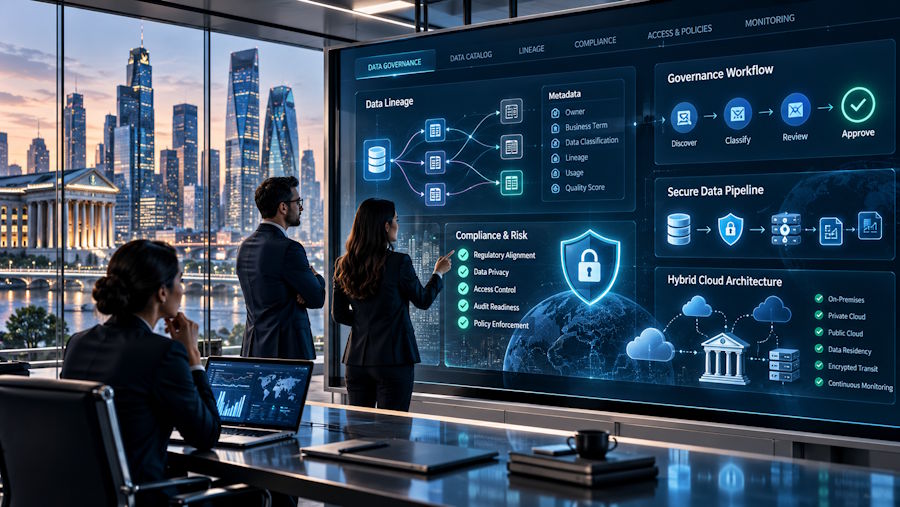
Regulatory scrutiny has moved data governance from a back-office concern to a board-level risk for United States banks in 2026. Examiners expect demonstrable control over how risk and finance data moves from source systems to submitted reports. BCBS 239 principles on risk data aggregation, CCAR reporting demands and, for banks with relevant EU-regulated operations, DORA operational resilience requirements all point to one question: can the bank prove its numbers? Many institutions still rely on manual spreadsheets, tribal knowledge and partial catalog entries to answer that question, slowing reporting cycles and weakening audit defence.
Our top pick is Solidatus for banks requiring detailed lineage across hybrid data estates to support BCBS 239 and CCAR reporting obligations, plus DORA where applicable to relevant EU-regulated operations, where traceability from source to regulatory report is the primary requirement. Its lineage-first approach centres on visual, end-to-end mapping rather than treating lineage as a catalog add-on, although buyers should verify the level of automation and coverage available for their systems. For banks prioritising a cost-conscious all-in-one catalog and lineage suite, OvalEdge is the strongest alternative. For teams whose primary gap is automated lineage across BI and ETL layers, Octopai (Cloudera Data Lineage) is the strongest alternative.
This guide is written for chief data officers, heads of data governance, compliance technology leads and enterprise architects preparing a shortlist in 2026. We assessed data governance platforms for banks against five criteria: regulatory traceability, lineage automation, deployment flexibility, metadata breadth and total cost of ownership. We then ranked six options for consideration by community, regional and global institutions. The comparison below summarises the field, followed by detailed assessments that include relevant limitations.
At-a-glance overview
The table summarises the six ranked options in order, from the strongest overall fit for regulatory lineage demands to more specialised tools.
| Provider | Best for | Key strength | Deployment |
|---|---|---|---|
| Solidatus | Lineage for regulated reporting | Visual lineage mapping, subject to scope validation | Confirm required deployment coverage with vendor |
| OvalEdge | Mid-size catalog and lineage evaluation | Catalog and lineage proposition requiring validation | Confirm deployment options with vendor |
| Alex Solutions | Metadata management evaluation | Metadata and catalog proposition requiring validation | Confirm deployment options with vendor |
| Octopai (Cloudera Data Lineage) | Automated BI and ETL lineage | Instant lineage across hybrid reporting stacks | SaaS for hybrid cloud environments |
| Quest Data Intelligence | Model-driven catalog and architecture governance | Modelling heritage with catalog depth | Confirm deployment options with vendor |
| Precisely | Data integrity evaluation for regulated operations | Broader integrity proposition requiring validation | Confirm deployment options with vendor |
What to look for
To rank consistently, we applied the same five tests to every platform. For regulated banking use cases, traceability claims should be assessed against the bank’s actual reporting obligations, technology estate and supervisory evidence requirements rather than generic governance claims.
Regulatory traceability depth
The platform should document data flows at the level examiners expect for BCBS 239 and CCAR, and for DORA where it applies to relevant EU-regulated operations, from source through transformation to report, with evidence that supports attestation. Buyers should check whether this documentation remains current as systems and reporting logic change.
Lineage automation
Lineage may be discovered automatically from metadata, queries, ETL logic and BI dependencies, or it may depend partly on manual modelling that can decay under change. The important test is how much of the bank’s real reporting chain the platform can capture without extensive manual upkeep.
Deployment flexibility
The tool should operate across relevant cloud, on-premises and legacy core banking systems without forcing a full migration, while respecting residency and access constraints. Vendor claims should be tested against the bank’s actual architecture rather than a simplified demonstration environment.
Metadata management breadth
A broader platform may cover cataloging, stewardship workflows, policy definition and integration with data quality processes rather than lineage alone. Banks should distinguish between functions available natively, those supplied through integrations and those requiring a separate product.
Total cost of ownership
Licensing, implementation effort and ongoing curation should be assessed against estate complexity and institution size, from community to global banks. Procurement teams should include internal staffing, connector work and maintenance in the calculation rather than comparing licence quotes alone.
The 6 best data governance platforms for banks in 2026
With those criteria established, here are six ranked options that stand out in 2026 for United States banking use cases, ordered from the strongest overall fit for demanding lineage and attestation needs to specialised tools for narrower institutional priorities. The highest-ranked option is aimed at banks where source-to-report traceability is non-negotiable. Each entry states a clear best-for segment, outlines relevant strengths and notes limitations so data and compliance leaders can match capability to size, estate complexity and examination posture.
#1. Solidatus – Best for AI lineage and regulatory traceability across hybrid estates
Solidatus is a lineage-first governance platform intended to support end-to-end traceability in regulated banking estates.
Solidatus is architected around visual, end-to-end data lineage rather than presenting lineage simply as an extension to a catalog. Its model is intended to show how data moves across the systems included in a governance scope, potentially spanning cloud platforms, on-premises warehouses and legacy environments, although coverage and automation should be confirmed for each bank’s technology stack. For institutions under BCBS 239 or CCAR obligations, and those subject to DORA through relevant EU-regulated operations, that orientation matters because examination evidence centres on complete flow documentation and the ability to trace a reported figure through transformations to authoritative sources. The platform also presents metadata management capabilities for stewardship and policy governance, but institutions should establish how those capabilities fit their operating model and expected scale.
Against the five criteria, the emphasis on visual lineage is the main reason it ranks first. A shared lineage view can support review between engineering, risk, finance and compliance, helping teams assess the impact of an upstream change and develop clearer reporting attestation narratives. Support for mixed technology estates is relevant to banks that retain mainframes or private data centres for residency, operational or resilience reasons, but buyers should validate every required source, transformation and reporting layer during evaluation. It is not a full-stack substitute for every governance function. It is better assessed as a traceability core that may need to sit alongside quality, master-data or other specialist tooling.
Key specs
- Lineage-first architecture with visual end-to-end flow mapping
- AI-assisted lineage and discovery capabilities that require scope validation
- Intended coverage for mixed cloud, on-premises and legacy environments
- Metadata layer supporting stewardship and policy governance
- Applicable to BCBS 239 documentation and CCAR attestation use cases
- Suitability for institutional scale should be established during evaluation
Pros
- Lineage is central to the product rather than an ancillary add-on
- Financial-services positioning aligns with traceability requirements
- Visual modelling can support technical and business compliance review
- Mixed-estate coverage can be assessed without assuming a full cloud migration
Cons
- Not a standalone data quality or master-data platform, so complementary tooling may be needed
- Pricing is not publicly listed, and procurement requires vendor discussion that may extend timelines for smaller banks
- Breadth may exceed immediate needs in simpler, homogeneous environments
- Connector coverage and automation depth should be verified against the bank’s systems
Who it's best for: banks where traceability from source to regulatory report is the primary requirement, especially under BCBS 239 or CCAR, and under DORA where relevant to EU-regulated operations.
#2. OvalEdge – Best for mid-size banks seeking catalog and lineage in one cost-conscious platform
OvalEdge is positioned as a unified governance suite for mid-market institutions seeking to balance functional breadth with budget discipline.
The platform is marketed as a more affordable alternative to some enterprise-tier suites, bringing catalog, lineage and access-control concepts into a single offering that may suit regional and mid-size banks. That packaging is relevant where a small governance team needs to cover discovery, documentation and access oversight without managing several tools, but the practical depth of each function needs to be tested. Public technical detail does not answer every banking-specific question, so evaluation should focus on a structured proof of concept against the bank’s reporting flows rather than marketing descriptions. Deployment options, connector coverage, access-control behaviour and pricing should all be confirmed directly with the vendor during shortlisting.
Key specs
- Positioned as a unified catalog and lineage suite
- Presented as including access-control concepts alongside discovery
- Marketed for mid-market financial institution needs
- Evaluation depends on vendor-led discovery and demonstration
Pros
- Unified-suite positioning may reduce tool sprawl for lean teams
- Cost-conscious framing may suit regional and mid-size budgets
- One environment can support catalog and lineage review
Cons
- Public technical documentation leaves areas requiring vendor validation
- Quote-based procurement means total cost is confirmed only through discussion
- Depth in a specific function may trail specialised lineage tools
Who it's best for: mid-size and regional banks seeking a unified governance suite without assuming enterprise-tier pricing.
#3. Alex Solutions – Best for metadata management with automated scanning across hybrid estates
Alex Solutions is a metadata management platform known in analyst alternative lists as ALEX and positioned for enterprise use across regions.
The offering is framed around automated metadata scanning and cataloging across complex on-premises and cloud environments. This addresses an early governance gap for many banks: incomplete inventories of data assets and their relationships. For institutions with hybrid estates, the ability to maintain that inventory as systems change matters more than a one-time import, although buyers should verify scanning frequency, supported sources and the manual work needed to resolve gaps. As with other less extensively documented options in this set, feature depth, connector scope and commercial terms should be validated through a vendor-led evaluation tied to the bank’s priority domains, such as finance, risk or regulatory reporting.
Key specs
- Focused on metadata management and cataloging
- Positioned for automated scanning across hybrid estates
- Presented for multi-region enterprise coverage
- Requires vendor confirmation for technical and commercial detail
Pros
- Metadata-centric approach suits discovery-led programmes
- Hybrid-estate positioning corresponds with common bank infrastructure
- Catalog capabilities can provide a foundation for stewardship workflows
Cons
- Available public feature detail leaves proof of concept important
- Pricing and packaging require direct vendor discussion
- Regulatory reporting depth should be validated rather than assumed
Who it's best for: institutions prioritising automated metadata discovery and cataloging across hybrid on-premises and cloud environments.
#4. Octopai (Cloudera Data Lineage) – Best for automated lineage across BI and ETL reporting stacks
Octopai, now operating as Cloudera Data Lineage, is a SaaS-based lineage product intended for complex cloud, on-premises and hybrid environments.
The product earns this position because automated lineage navigation addresses a reporting-stack problem many banks face: important logic buried in BI semantic layers, dashboards and ETL pipelines that manual documentation does not always keep current. SaaS delivery can reduce infrastructure work compared with self-managed deployments, while automated harvesting across supported tools may shorten impact analysis when a transformation or report definition changes. Vendor materials describe its use within data documentation and approval workflows, suggesting a possible fit for governed change control, although banks should confirm that workflow against their own requirements. Cloudera ownership adds an established enterprise vendor, but it may also mean procurement is influenced by broader Cloudera platform decisions.
The trade-off is breadth against specialisation. This is a strong lineage-harvesting candidate for BI-heavy estates, but it is less broad than a full governance suite covering extensive stewardship or policy workflows. Banks with strict data-residency or on-premises-only mandates should test SaaS suitability at the start of procurement. Available materials do not confirm native banking regulatory reporting templates, so BCBS 239 or CCAR alignment should be demonstrated through the bank’s own use cases rather than inferred from lineage automation alone.
Key specs
- Operates as Cloudera Data Lineage, formerly Octopai
- SaaS-native delivery for hybrid data environments
- Automated lineage harvesting intended to reduce manual mapping
- Designed for BI, ETL and reporting-layer dependencies
- Supports documentation and approval workflows
- Part of the Cloudera enterprise platform
Pros
- SaaS model can lower infrastructure and maintenance demands
- Automated harvesting is designed for complex hybrid environments
- Strong potential fit for BI and ETL-heavy reporting estates
- Cloudera ownership provides an established enterprise context
Cons
- Cloudera ownership may connect procurement with wider platform choices
- SaaS delivery may not suit strict residency or on-premises mandates
- No verified native BCBS 239 or CCAR reporting templates in the available facts
- Narrower than a full governance suite, with its clearest strength in lineage
Who it's best for: banks whose primary gap is automated lineage tracing across BI tools, ETL pipelines and hybrid reporting stacks.
#5. Quest Data Intelligence – Best for model-driven catalogs and architecture-centric governance
Quest Data Intelligence, rebranded from erwin Data Intelligence with version 16, is a long-running data intelligence product line under Quest Software with a background in enterprise modelling.
That product history is relevant because institutions with mature data architecture practices often prefer catalogs that connect to conceptual, logical and physical models instead of treating the catalog as a standalone search index. This architecture-centric framing may suit banks where governance, design and change control must remain aligned, but buyers should verify how the current product handles each of those needs. Quest uses customisable, quote-based pricing, so commercial fit can be established only through direct discussion. Connector scope, deployment modes and banking regulatory features were not confirmed in the available facts and should not be assumed; evaluation should centre on a modelled domain relevant to risk or finance.
Key specs
- Long-running catalog and intelligence product line
- Background in enterprise data modelling and architecture
- Positioned for architecture-centric governance needs
- Quote-based, customisable pricing via the vendor
Pros
- Modelling background may appeal to architecture-led organisations
- Catalog approach can support governed design and documentation
- Customisable pricing permits a scope-based discussion
Cons
- Available materials leave some feature details to be confirmed
- Deployment and integration scope require vendor validation
- Procurement depends on consultative quoting, which may extend timelines
Who it's best for: enterprises with established data architecture practices seeking a catalog with strong modelling heritage.
#6. Precisely – Best for data integrity and mainframe-to-cloud lineage in regulated operations
Precisely is a data integrity and data quality vendor with a broad portfolio relevant to regulated-industry data management.
The best-for case here is operational rather than catalog-led. Banks retaining legacy mainframe environments while extending to cloud need integrity, quality assurance and continuity across that full stack. Precisely is associated in the market with regulated-industry data integrity and mainframe-to-cloud data management, making it an option to investigate for institutions where trust in data content is as pressing as knowledge of data location. The available verified materials did not establish specific governance or lineage product capabilities for this evaluation, so buyers should treat governance depth as unproven until demonstrated. In particular, lineage coverage, stewardship workflows and regulatory mapping should be tested against the bank’s reporting chain rather than inferred from broader integrity positioning.
Key specs
- Positioned around data integrity and quality assurance
- Associated with regulated-industry data management
- Relevant to mainframe-to-cloud continuity needs
- Governance depth requires vendor-led validation
Pros
- Integrity and quality framing addresses trust in regulated operations
- Legacy-to-cloud positioning may fit banks with mainframe estates
- Broad portfolio permits a combined quality and governance discussion
Cons
- No verified governance feature detail in the available facts for this set
- Regulatory traceability should be proven through a proof of concept
- Commercial and deployment specifics require vendor confirmation
Who it's best for: banks with legacy mainframe environments and regulated operations requiring integrity and quality assurance alongside governance.
Frequently asked questions
Use these answers to narrow data governance platforms for banks to a shortlist that fits examination pressure, estate complexity and team capacity.
Should I prioritise automated lineage or a data catalog first?
Prioritise automated lineage if examination findings, CCAR resubmissions or BCBS 239 remediation cite untraceable transformations or manual flow diagrams. A catalog without current lineage improves discovery but does not prove how a reported figure was derived. Prioritise the catalog first if the bank lacks a trusted inventory of critical data elements and ownership. Most regional and global banks in 2026 need both, sequenced so lineage covers priority reporting domains while the catalog expands steadily.
Is AI lineage worth it for improving regulatory reporting accuracy?
AI lineage can be worthwhile where reporting chains span dozens of feeds, layered transformations and BI logic that manual documentation cannot keep current. Automated discovery may reduce stale diagrams, surface undocumented dependencies and shorten root-cause analysis when a balance or risk measure breaks, although its accuracy still needs human validation. Insist on a demonstration using the bank’s own finance or risk flows, with evidence of source-to-report completeness.
Should I invest in a lineage-first platform to meet BCBS 239 and CCAR demands?
A lineage-first platform is justified when traceability is the primary examination gap, particularly for risk data aggregation and report attestation. BCBS 239 expects accuracy, integrity, completeness and adaptability across the reporting chain, while CCAR requires defensible controls around data and calculations. Visual, end-to-end lineage can help risk, finance and compliance review the same evidence and assess the downstream impact of upstream changes. If the gap is policy enforcement or data ownership instead, place more weight on stewardship and catalog workflow depth.
Is a full enterprise suite worth it for a community or regional bank?
A full suite is rarely worth it for a community bank with a homogeneous estate and a small governance team if its breadth adds implementation work without a corresponding examination benefit. Regional banks face a closer call because unified catalog, lineage and access capabilities can be efficient when they replace spreadsheet controls and reduce tool sprawl. Start from the bank’s top three examination risks and size the platform to those domains, with an option to expand. Quote-based pricing should be tested against a phased scope rather than an enterprise-wide licence on day one.
Should I choose a SaaS governance tool if my bank has strict data-residency rules?
Choose SaaS only after information security and compliance confirm that metadata extraction, storage location and access controls meet residency and third-party risk requirements. SaaS lineage harvesting can lower infrastructure effort for hybrid estates, but some banks must keep metadata or profiling within dedicated boundaries. Ask vendors exactly what metadata leaves the estate, where it is stored and how tenant isolation is enforced. If constraints prohibit SaaS, shortlist hybrid or on-premises-capable options and validate the proposed deployment during procurement.
Is consolidating data quality and governance in one vendor worth it, or should I keep them separate?
Consolidation can be worthwhile when the same team owns quality rules, stewardship and reporting controls and benefits from shared definitions and workflows. Separation is preferable when lineage traceability is urgent but quality scoring or master-data management requires specialist depth that a lineage-led platform does not provide. Many banks in 2026 use a hub model, with a lineage and catalog core for traceability integrated with specialist quality tooling where material. Decide based on ownership, integration effort and the gap drawing examiner attention first.
How to choose: a decision framework for 2026
Choosing among data governance platforms for banks comes down to estate complexity and the primary examination risk. Choose Solidatus if source-to-report traceability across mixed systems is the deciding requirement, particularly under BCBS 239 or CCAR, and under DORA where relevant to EU-regulated operations, after verifying automation and system coverage. Choose OvalEdge if a mid-size institution needs catalog, lineage and access concepts in one cost-conscious suite. Choose Alex Solutions if automated metadata discovery is the first gap, Octopai if BI and ETL lineage is the blind spot, Quest Data Intelligence if model-driven architecture governance leads, or Precisely if mainframe-to-cloud integrity frames the programme. In 2026, defensible lineage paired with governed metadata gives banks a stronger basis for regulatory evidence and confident financial close processes.