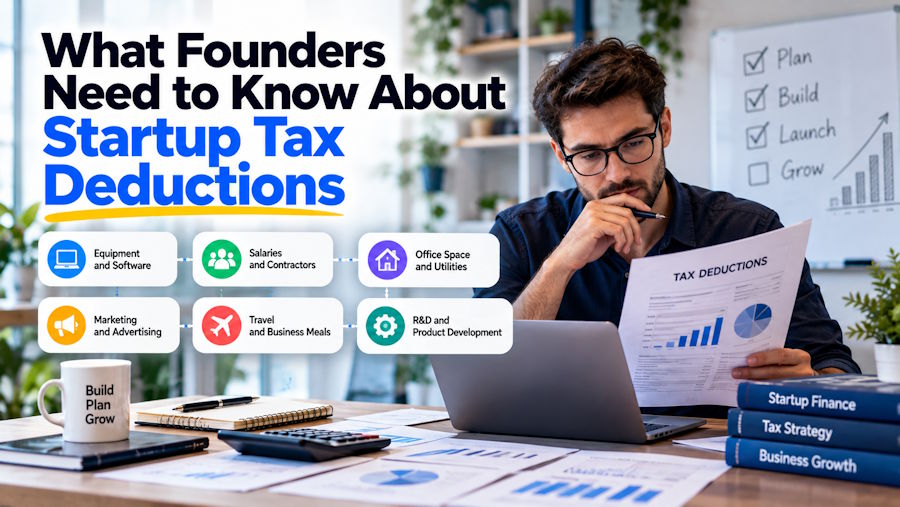
Startup tax deductions lower your overall tax bill by letting you subtract pre-launch and daily business expenses from your total revenue. Knowing how to claim these tax write-offs helps founders save cash and extend their company's runway.
Timing determines how the Internal Revenue Service (IRS) handles your startup spending. Special setup rules apply to money spent before your official opening date. Costs paid after you open your doors count as standard operating expenses. Your official opening date creates a clear dividing line for every receipt.
| Expense Category | IRS Tax Rule | First-Year Tax Treatment |
|---|---|---|
| Pre-Launch Costs | Section 195 | Deduct up to $5,000 upfront. Amortize the rest over 15 years. |
| Post-Launch Costs | Section 162 | Deduct 100 percent of standard operating costs in the current year. |
Pre-Launch Section 195 Deductions
Pre-launch Section 195 deductions let new business owners write off up to $5,000 in early startup setup costs during their first active operational year. The IRS requires you to spread out any remaining setup costs over 15 years through equal yearly tax deductions. This category covers expenses like market research, vendor travel, and early staff training.
Tracking the exact date your business becomes active creates confusion for many founders, leading to these tax write-offs being missed. Always keep accurate receipts throughout this phase so every qualifying dollar reduces your overall tax bill.
7 Essential Startup Deductions
The seven essential startup tax deductions cover both your initial pre-opening setup costs and the daily operating expenses needed to run your business. Claiming these core write-offs reduces your overall tax liability, so you keep more capital in the company.
1. Pre-Launch and Organizational Expenses
Pre-launch costs cover the money you spend to research, set up a legal entity, and form a business before opening. These qualifying setup expenses follow Section 195 upfront deduction rules.
2. Laptops, Servers, and Hardware
Computers, servers, and office desks form the physical tools your team needs to work daily. Section 179 lets you write off the full cost of this equipment in year one instead of stretching the deduction over five years.
3. Research & Development Tax Credits
Building new software, patents, or physical products unlocks the federal research and development tax credit under Section 41. Startups can apply these credits directly against up to $500,000 in payroll taxes each year, providing instant cash savings even before making a profit.
Kevin DeCicco is a CPA and the Managing Tax Partner at Florida accounting firm Alpine Mar, which specializes in CPA services for startups. DeCicco explains how pre-revenue companies capture immediate cash flow from this incentive:
"The payroll tax credit allows qualified small business startups to apply R&D tax credits against employer-paid Social Security and Medicare taxes to receive a maximum of $500,000 in annual cash savings. This allows pre-revenue companies to get immediate liquidity instead of waiting until they are profitable."
DeCicco highlights why VCs and founders view R&D credits as a crucial fundraising advantage:
"Investors use the R&D tax credit as a key metric for capital efficiency because it directly lowers a startup's burn rate and extends its cash runway. Every $100,000 in credits is $100,000 less to raise from venture capitalists, protecting your ownership stake and proving you are optimizing non-dilutive capital."
4. Legal and Accounting Fees
Attorneys, CPAs, and bookkeepers keep your startup legally safe and financially organized. You’re allowed to write off the professional fees you pay for drafting contracts, filing incorporation papers, and preparing tax returns as standard business expenses.
5. SaaS and Cloud Subscriptions
Modern businesses rely on software and online services to run their daily operations. Monthly subscriptions for Google Workspace, AWS hosting, GitHub, and payment tools count as direct operating expenses that reduce your income in the year you pay them.
6. Marketing and Customer Acquisition
Finding your first paying customers requires consistent spending across digital and print channels. Ad campaigns, website design, domain name registration, and PR work count as deductible marketing costs in the year they run.
7. Home Office and Coworking Costs
Founders working from home should write off a portion of their housing expenses if they use a specific room only for business. The IRS offers a simple method that allows a deduction of $5 per square foot up to 300 square feet. Rent paid for dedicated desks in coworking spaces is also deducted fully as a business expense.
How Do Investor Tax Incentives Help Startups Raise Capital?
While operating deductions lower your company's immediate tax bill, investor tax rules make your startup significantly more attractive to early backers. Structuring your business to meet IRS rules like Section 1244 and Section 1202 gives angel investors powerful tax shields, making it easier to close your seed round.
Section 1244 Protects Investor Capital
IRS Section 1244 protects your early investors by letting them deduct stock losses directly against their regular income if the business unfortunately fails. Single filers can claim up to $50,000, while joint filers can claim up to $100,000 in ordinary losses.
While initial equity investments are not direct business expense deductions, Section 1244 converts capital losses into ordinary losses for your backers. This bypasses the standard $3,000 annual cap on capital losses, which lowers their financial risk.
To ensure your shares offer this tax protection to your investors, your startup must meet these IRS rules:
- Direct Issuance: Shares must go directly to individual investors, not through holding LLCs (limited liability companies) or investment funds.
- Capital Cap: Total equity money raised must stay under $1 million at the time of stock issuance.
- Active Business: More than half of your startup's income must come from real operations, not passive sources like rent or royalties.
Section 1202 QSBS Rules Benefit Early Investors
Section 1202 Qualified Small Business Stock (QSBS) rules allow investors to pay zero federal capital gains tax when selling qualified startup shares held for at least five years. Smart founders plan for this tax-free exit right from incorporation to attract long-term angel and venture capital investors.
To offer QSBS benefits, your company must operate as a C corporation with gross assets under $50 million when issuing the stock. Maintaining clean corporate records across every funding round ensures your early backers keep 100 percent of their profits tax-free up to $10 million when they exit.
How Do Startups Maintain Tax Compliance?
Startups maintain tax compliance by saving itemized receipts and tracking exact transaction dates. Founders should store digital copies that can be retrieved and reproduced under official IRS record standards if audited. Maintaining general expense receipts for three years and payroll tax records for at least four years ensures your write-offs stand up under review.
When claiming complex tax incentives like R&D credits, real-time recordkeeping becomes mandatory. DeCicco warns against delaying documentation until the end of the year:
"You must keep contemporaneous documentation—meaning you need to prove the work happened while it was actually being done. If you wait until tax season to remember what your team worked on last year, you risk losing the credit entirely."
Commingling personal and business money breaks legal liability protections and causes tax officers to reject your write-offs. Open a dedicated business bank account on day one, and verify that every claimed cost qualifies as an ordinary and necessary business expense.
Smart Tax Planning Powers Startup Growth
Early tax planning keeps critical capital inside your business from day one. These strategic deductions give your team extra runway to hire talent and build products. Taking full advantage of these rules protects both your cash flow and your early investors.
However, your tax write-offs are only useful if they survive an IRS review. Be sure to open a dedicated bank account on day one to protect your liability shield. Then store your digital receipts so that every deduction remains safe, and your capital stays where it belongs.