Debt has a way of creeping up on you. A few purchases on your credit card, an unexpected car repair, or a couple of expensive months can leave you juggling repayments that barely seem to reduce what you owe. Even when you're making regular payments, it can be difficult to see a clear path towards becoming debt-free.
Artificial intelligence is making that process easier to manage. Rather than manually sorting through bank statements or building complicated spreadsheets, you can use AI-powered tools to understand your spending, identify opportunities to save, and develop a realistic repayment strategy. Some tools can even help you compare financial options, including debt consolidation loans, to determine whether combining existing debts could make repayments more manageable.
AI won't magically eliminate your debts, but it can help you make better decisions with the money you already have. Here are five practical ways to put it to work.
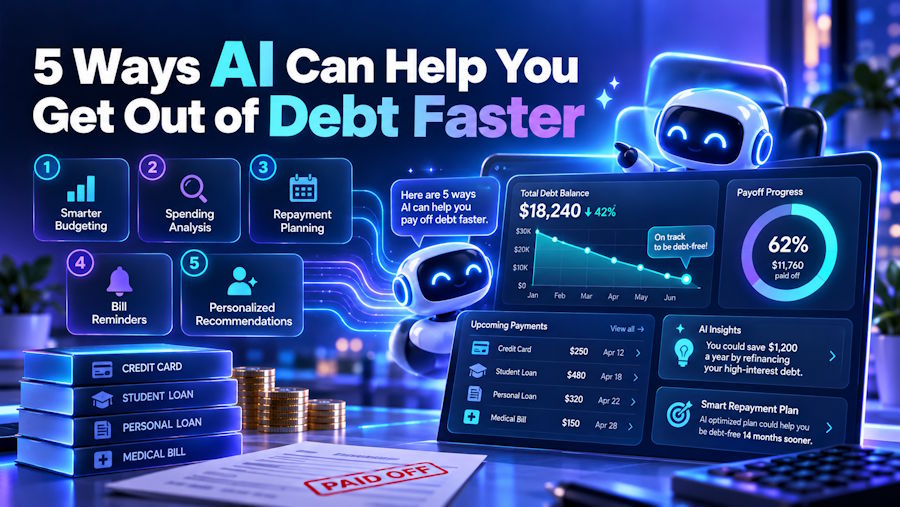
1. Find Out Where Your Money Is Actually Going
Most people have a reasonable idea of their major expenses. Rent, groceries, transport and utilities are easy to remember. It's the smaller, less obvious purchases that often go unnoticed.
AI-powered budgeting apps can analyse transaction histories and automatically organise spending into categories. Instead of spending hours reviewing bank statements, you can quickly see how much you're spending on takeaway meals, subscriptions, shopping and other everyday expenses.
Start by reviewing three months of transactions. Look for recurring payments you no longer need or categories where your spending has gradually increased.
The objective isn't to eliminate everything enjoyable from your budget. It's to identify a few manageable changes that could free up additional money for debt repayments.
2. Build a Repayment Plan That Fits Your Budget
Knowing how much you owe is one thing. Figuring out which debt to tackle first is another.
AI assistants such as ChatGPT can help you organise your debts and explore different repayment strategies. Provide the balances, interest rates, minimum repayments and amount you can afford to pay each month.
You can then ask the assistant to compare two common approaches:
- Debt avalanche: Paying extra towards the debt with the highest interest rate first, potentially reducing your overall interest costs.
- Debt snowball: Paying off your smallest balance first, which can provide motivation as individual debts disappear.
For example, you might discover that directing an extra $100 towards a high-interest credit card could make a meaningful difference over time.
AI-generated calculations aren't always accurate, so verify the repayment figures using a reliable financial calculator before making decisions.
3. Predict Expensive Months Before They Happen
One reason debt can be difficult to escape is that unexpected expenses keep disrupting your progress.
However, plenty of supposedly unexpected costs are actually predictable. Car registration, insurance renewals, annual subscriptions and seasonal expenses often arrive around the same time each year.
Some AI-powered financial tools can examine historical transactions and identify recurring patterns. This information can help you anticipate months when your expenses are likely to increase.
You can also create your own forecast using an AI assistant. List your upcoming bills, expected income and regular spending, then ask it to organise everything into a monthly cash-flow plan.
Setting aside smaller amounts throughout the year could prevent you from relying on credit when larger bills arrive.
4. Use AI to Find Savings You're Overlooking
Reducing debt doesn't always require earning more money. Sometimes, improving how you manage existing expenses can be equally valuable.
AI can help you review spending habits and identify practical opportunities to save without making drastic lifestyle changes.
For instance, you could provide an anonymised breakdown of your monthly expenses and ask:
"Where could I realistically reduce my spending by $150 per month without changing my essential expenses?"
The assistant might suggest reviewing unused subscriptions, comparing insurance premiums, reducing food waste or renegotiating certain service contracts.
Treat these recommendations as starting points rather than guaranteed savings. You'll still need to check actual prices and decide which changes make sense for your circumstances.
Avoid uploading bank account numbers, passwords or other sensitive financial information into general-purpose AI tools.
5. Track Your Progress and Stay Motivated
Paying off debt can take months or years, particularly when interest charges absorb a significant portion of each repayment.
That makes tracking progress important.
AI-powered budgeting tools can help you monitor declining balances, compare actual repayments against your goals and identify when your strategy needs adjusting.
Consider setting a monthly reminder to review your finances. Record how much debt you've repaid, whether your spending stayed within budget and how much extra you managed to contribute.
You could also use an AI assistant to create a simple progress dashboard showing your remaining balances and estimated repayment timeline.
Seeing tangible progress can make it easier to stay committed, even when the process feels slow.
Make Technology Work for Your Financial Goals
AI is most useful when it helps you turn financial information into practical decisions. It can highlight spending patterns, organise repayment strategies and make it easier to prepare for future expenses.
However, no algorithm understands your circumstances perfectly. Interest rates, fees, income changes and personal priorities all affect which financial decisions are right for you.
Start with one manageable task, such as analysing your recent spending or organising your outstanding debts. Use the insights to make a small improvement, then build from there.
Getting out of debt still requires consistency and discipline. AI simply gives you another set of tools to make the journey more manageable.