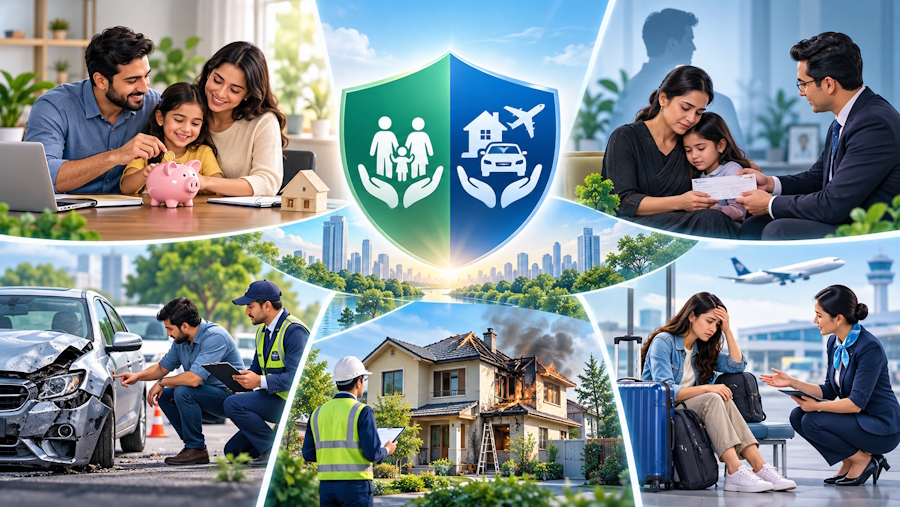
Most people think all insurance works the same way. Buy a policy. Something bad happens. Get money back. But that's not how it works at all. Life insurance and general insurance solve completely different problems. Real situations show exactly why you need to understand the difference. These aren't just theoretical concepts. Real families face these scenarios every single day and realise too late what they're actually missing.
Scenario 1: The 45-Year-Old Earner With a Family
Raj is 45 years old. He earns ₹1.5 lakh monthly. He's got a wife, two kids, a home loan with ₹30 lakh remaining, and car payments.
One morning, he has a heart attack. He survives but loses his job during recovery. His family needs him to keep earning. Medical bills are ₹5 lakh. The car loan needs to be paid every month. The home loan needs to be paid. Monthly expenses are ₹60,000. Bills don't stop coming.
If Raj had used a term plan calculator and bought ₹1 crore life insurance, he'd be fine. His family could survive while he recovers and finds a new job. But he doesn't have life insurance. He has general insurance covering his car and house. That insurance doesn't pay anything when he can't work. The family's in serious trouble.
Life insurance would have protected against losing income. General insurance protects against property loss only.
Scenario 2: The House Fire That Destroys Everything
Priya owns a house worth ₹50 lakh. She's got general insurance covering fire, theft, and natural disasters. One night, faulty wiring causes an electrical fire. The house burns down completely.
Priya files a claim with her general insurance. The company inspects and pays ₹45 lakh to rebuild. That's what general insurance does. It covers physical property damage.
But general insurance doesn't replace lost income if someone died in the fire. It doesn't support the family financially if something happened to Priya during that fire. General insurance is purely about property, not about protecting people's financial futures. If Priya's elderly parents depended on her income, they'd still struggle.
If Priya had life insurance, it would protect her family's finances. General insurance protects her house.
Scenario 3: The Car Accident That Changes Everything
Vikram is driving home from work when a truck hits his car at an intersection. The car is completely totaled. The insurance company writes it off. Vikram survives but has serious injuries. He needs two major surgeries. Hospital stays last 45 days. Medicines for months afterward. Physical therapy for recovery. Medical costs total ₹20 lakh.
Vikram's general insurance covers his car damage. The insurance company pays ₹12 lakh toward a new car because that's the limit on his policy. But the medical bills? General insurance on the car doesn't cover those at all. Understanding the difference between life insurance and general insurance becomes crystal clear when facing both medical costs and car damage simultaneously.
Vikram's car is replaced. But his family drowns in medical debt because he has no health insurance coverage. Life insurance wouldn't help here because he's alive. What Vikram actually needed was health insurance for the medical costs and general insurance for the car. He only had car insurance, and now he's paying ₹20 lakh out of pocket.
Scenario 4: The Unexpected Death That Leaves Everything Behind
Anil is 50 years old. He's got ₹2 crore in savings. His house is fully paid off. No loans. No debts. His kids are working and independent. He's got general insurance on his house and car covering damage and theft. He doesn't have life insurance because he thinks he doesn't need it with all his money saved.
One day Anil has a massive stroke and dies suddenly. His family grieves. His wife has his savings. The house is hers. The car is hers. Everything he owns transfers to his family legally.
But here's the problem nobody expected. Anil had outstanding medical bills from his emergency treatment. ₹15 lakh in hospital costs for the stroke treatment. His life insurance would have covered that from the death benefit. His general insurance covers the car and house but nothing else. The family ends up using some of his hard-earned savings to pay medical expenses that life insurance would have handled cleanly.
Scenario 5: The Business Owner With Complicated Risks
Deepa owns a factory that produces textiles. She's got general insurance covering the building, machinery, inventory, and liability for workers. She's also got life insurance for ₹3 crore because she knows her family depends on her income. Her 200 employees depend on her to run the business.
One day a major fire breaks out in the factory during production. General insurance covers the building damage and machinery replacement. She can rebuild the factory. But Deepa also gets trapped in the fire and dies in the incident. Her life insurance pays ₹3 crore to her family. That money helps them survive financially and pay off outstanding business debts and loans.
Without life insurance, her family would struggle financially even though the business property got covered by general insurance. Her family would lose both her and face financial ruin. Without general insurance, the business couldn't rebuild even if Deepa survived. Both types of insurance were necessary because the risks were completely different.
Why Both Types Actually Matter
These scenarios show the reality clearly. Life insurance protects people and their financial future. General insurance protects property and assets. They're not interchangeable at all. Most families need both because life involves both people and property that need protection.
Disclaimer: This blog is for general information only and is not personalised insurance or financial advice. Life insurance and general insurance policies vary by provider and policy type. Coverage, exclusions, and premiums differ widely. Read policy documents carefully before purchasing. Consult a qualified financial advisor for your specific situation. For official insurance information, visit the Insurance Regulatory and Development Authority (IRDAI) at https://www.irdai.gov.in/.